Some Medicare mistakes cost you for life. Know them before your deadline does.
In 2026, missing Part B by two years costs $40.58 extra every month - for as long as you have Part B. This checklist walks you through the 10 decisions around 65 you can't easily undo: the official rule, your deadline, the real cost and the exact step for each.
The complete book — ready to go.
- The 10 Medicare mistakes that cost for life, each with the official rule and deadline
- The real 2026 cost of each mistake, with sources from Medicare.gov, SSA and CMS
- A tick-off checklist for every mistake
- The exact questions to ask HR, Social Security and any plan
- A 12-month deadline planner starting at your 64th birthday
- A page for grown children to go through it with a parent
- Instant access on any device
The book + audiobook + all bonus extras in one bundle.
Digital checklist book (PDF) · one-time payment · the 2027 edition is updated once CMS publishes the 2027 amounts
What is inside The Medicare Mistakes Checklist
Before You Start: The Clocks That Run Around Your 65th Birthday
- How to Use This Book
- Clock 1: The Initial Enrollment Period (IEP)
- Clock 2: Special Enrollment Periods (SEPs)
- Clock 3: The Medigap Open Enrollment Period
Mistake 1: Letting the Part B Initial Enrollment Period Pass
- What the Initial Enrollment Period Actually Is
- A Familiar Story
- The Part B Late Enrollment Penalty, Explained Precisely
- What This Looks Like in Real Dollars
Mistakes 2 and 3: Trusting the Wrong Employer Coverage
- The 20-Employee Line That Decides Everything
- Why the 20-Employee Rule Trips Up Reasonable People
- When It's Not Your Job, But Your Spouse's
- The Younger Spouse's Coverage Cliff
Mistake 4: Counting on COBRA or Retiree Coverage Instead of Part B
- The Word That Trips Everyone Up: "Coverage"
- Why COBRA and Retiree Plans Don't Count
- What Happens When the Clock Starts Anyway
- The Coverage Gap Nobody Warns You About
Mistake 5: Going Without Creditable Drug Coverage
- The Penalty Nobody Explains Until It's Too Late
- Why This Mistake Feels Invisible
- What "Creditable Coverage" Actually Means
- The Notice You're Supposed to Get Every Year
Mistake 6: Missing the Medigap Open Enrollment Window
- What Medigap Actually Is, and Why the Timing Matters So Much
- How the Six-Month Clock Actually Starts
- What Guaranteed Issue Actually Means
- A Composite Example: Two People, Two Timelines
Mistake 7: Choosing Medicare Advantage First Without Knowing the Way Back
- Two Paths, One Door That Swings Differently Each Way
- The 12-Month Trial Right: A Real Safety Net, But Only for Some
- What Happens After the Trial Right Expires
- Why This Isn't About Which Option Is Better
Mistakes 8 and 9: Being Surprised by IRMAA, and Not Appealing It
- The Letter Nobody Budgeted For
- How the Two-Year Lookback Actually Works
- The 2026 Income Brackets, Structurally Explained
- The One-Time Income Trap
Mistake 10: Keeping HSA Contributions Going After Medicare Starts
- Why HSAs and Medicare Cannot Coexist
- The Six-Month Trap That Makes This Mistake Different
- Who This Actually Affects
- The Official Rules, Plainly Stated
The 12-Month Deadline Planner: From Your 64th Birthday Onward
- Age 64, Twelve Months Out: Gather and Verify
- Eleven Months Out: The Employer Size Conversation
- Ten Months Out: The Drug Coverage Check
- Nine Months Out: COBRA and Retiree Coverage Reality Check
For Grown Children: Going Through It Together
- Why This Has to Be a "With," Not a "For"
- The Permissions You Need Before You Need Them
- The One-Page Family Medicare Sheet
- What Belongs to Your Parent Alone
Everything you need to turn 65 right
Part B Deadlines
The window that decides whether a penalty follows you.
Employer Coverage & COBRA
What still working really means for Medicare.
The Medigap Window
Why timing matters more than the plan itself.
Medicare Advantage First
What to check before choosing it as your first plan.
IRMAA & HSA
Income and savings decisions with a Medicare price tag.
For Grown Children
A guided page to go through it with a parent.
Some Medicare mistakes cost you for life. Know them before your deadline does.
In 2026, missing Part B by two years costs $40.58 extra every month - for as long as you have Part B. This checklist walks you through the 10 decisions around 65 you can't easily undo: the official rule, your deadline, the real cost and the exact step for each.
- Catch the deadlines that quietly close, before a lifetime penalty is added to your bill
- Walk into HR, Social Security or any plan with the exact questions instead of guessing
- Help a parent get this right now, instead of discovering the mistake when it can no longer be fixed
$26.99 $53.99 one-time payment · instant digital access
Does any of this sound familiar?
You are still working and assume you can wait
Employer coverage, COBRA, an HSA: each one changes what you must do at 65, and the rules are rarely explained up front.
Everyone gives you a different answer
HR says one thing, a plan salesperson another, a neighbor a third. Nobody puts the official rule and the deadline in front of you.
You are handling the paperwork for a parent
You want to protect them, but the letters, windows and acronyms pile up faster than you can check them.
“The expensive part of Medicare is rarely the choice itself. It is the deadline nobody told you about.”
Only in the Complete Package: your bonus extras
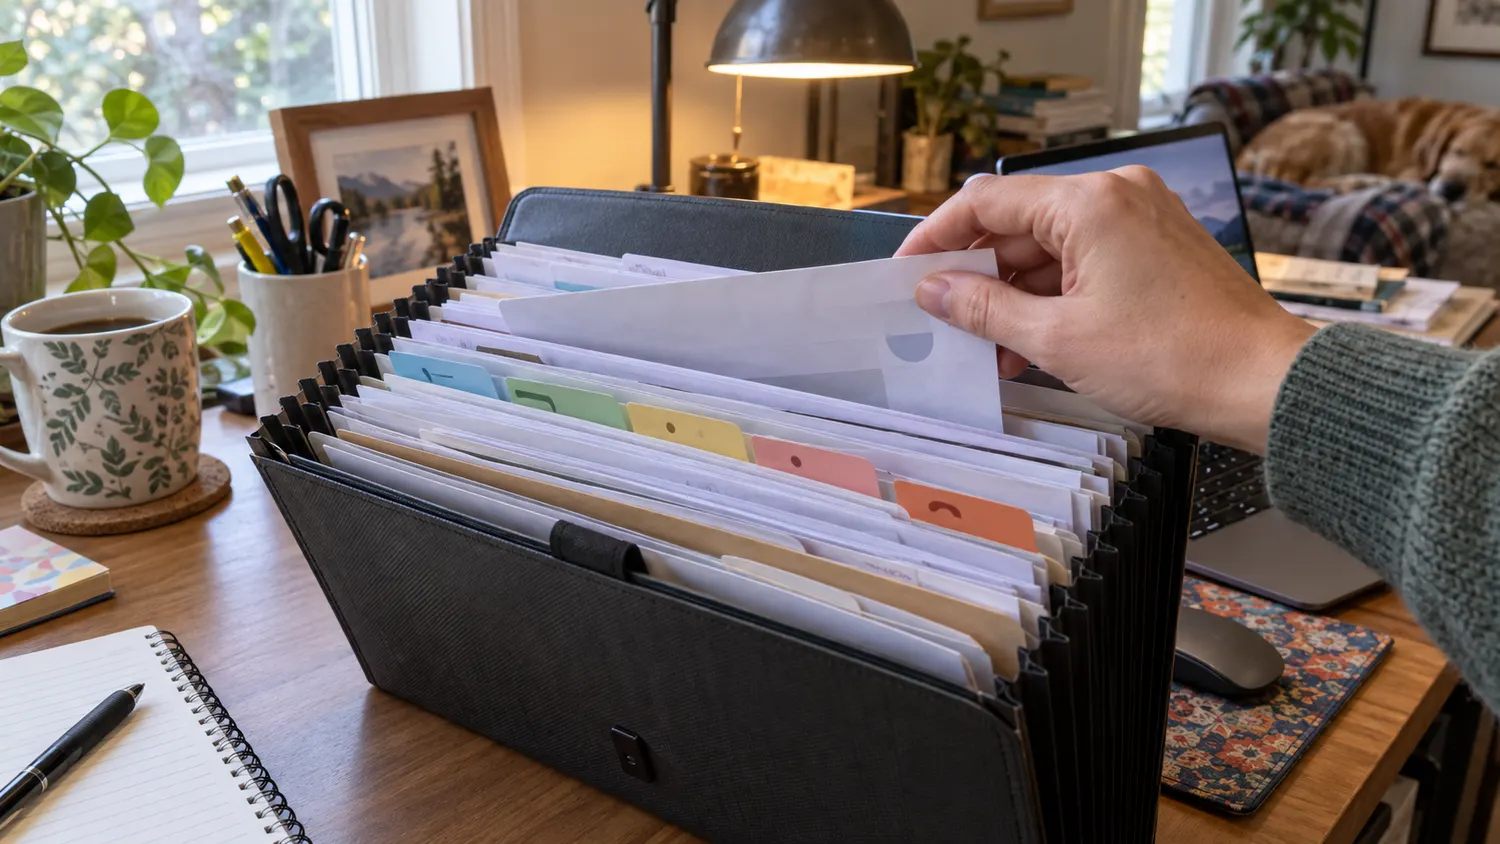
The Paper-Trail Vault: Proof-of-Coverage Organizer
Years from now, when Medicare questions a late enrollment, you can show dated proof of every creditable coverage instead of paying a lifetime penalty you never owed.
The Word-for-Word Call & Letter Script Kit
You avoid being brushed off by Social Security, HR or an insurer because you know exactly what to say, what to request in writing and what to write down before you hang up.
State-by-State Medigap Rights Dossier
You learn whether your state gives you extra ways back into Medigap after the national window closes, and you avoid losing an option you didn't know you had.
$26.99
What you will discover
- The deadline most people learn about too late
- Why still working does not always mean waiting
- The one window you cannot reopen later
- What to ask before choosing Medicare Advantage
- How your income quietly changes your premium
- The HSA detail that surprises people near 65
- The COBRA assumption that can cost for life
- The question HR often does not answer
- Which mistakes can still be fixed, and which cannot
- What to check with a parent this month
This checklist is for you if …
You are turning 65 soon
You want every rule and deadline in one place, before a window closes without warning.
You are still working past 65
You have employer coverage, COBRA or an HSA and need to know exactly what applies to you.
You handle the paperwork for a parent
You want a clear page to go through step by step together, so nothing slips.
Frequently asked questions
I am still working. Is this relevant for me?
Yes. Employer coverage, COBRA and an HSA each have their own chapter, with the official rule, the deadline and the questions to ask HR.
Do you sell Medicare plans or earn commissions?
No. I sell no plans and receive no commissions. The checklist is educational and points you to the official sources so you can verify every rule yourself.
Where do the figures come from?
Only from official sources such as Medicare.gov, SSA and CMS, and each figure is marked with its source. The 2027 edition is updated when CMS publishes the 2027 amounts.
Can I use it for a parent?
Yes. There is a dedicated page for grown children to go through the checklist together with a parent, step by step.
In what format do I get it?
As a PDF checklist book, readable and printable on computer, tablet and phone.
How do I receive it after purchase?
Right away by email, with a secure personal download link.
Is this personal advice for my situation?
No. It explains the federal rules and deadlines and shows you exactly what to ask. For your own case, confirm your dates with Social Security or your state's free SHIP counselor - the book tells you how and what to ask.
I am only 62 or 63. Is it too early?
No. IRMAA looks at your income from two years earlier, so decisions at 63 can raise your premium at 65. The deadline planner starts at your 64th birthday, and the HSA chapter tells you when to stop contributing.